HOA Deferred Maintenance: What Every Condo Buyer Should Know Before Making an Offer
A condominium may appear to be the perfect home on the surface. The landscaping is beautifully maintained, the lobby is spotless, and the monthly condominium fee seems reasonable. However, what many buyers don’t realize is that some of the most expensive problems can be hidden behind the walls—or delayed by years of postponed maintenance.
Deferred maintenance occurs when a homeowners association (HOA) or condominium association delays necessary repairs or replacements to common areas in order to keep monthly fees low or avoid large expenditures. While postponing repairs may seem like a short-term solution, it can create significant financial consequences for both current owners and future buyers.
If you’re considering purchasing a condominium, understanding how deferred maintenance affects property values, monthly fees, and future assessments is just as important as choosing the right floor plan or location.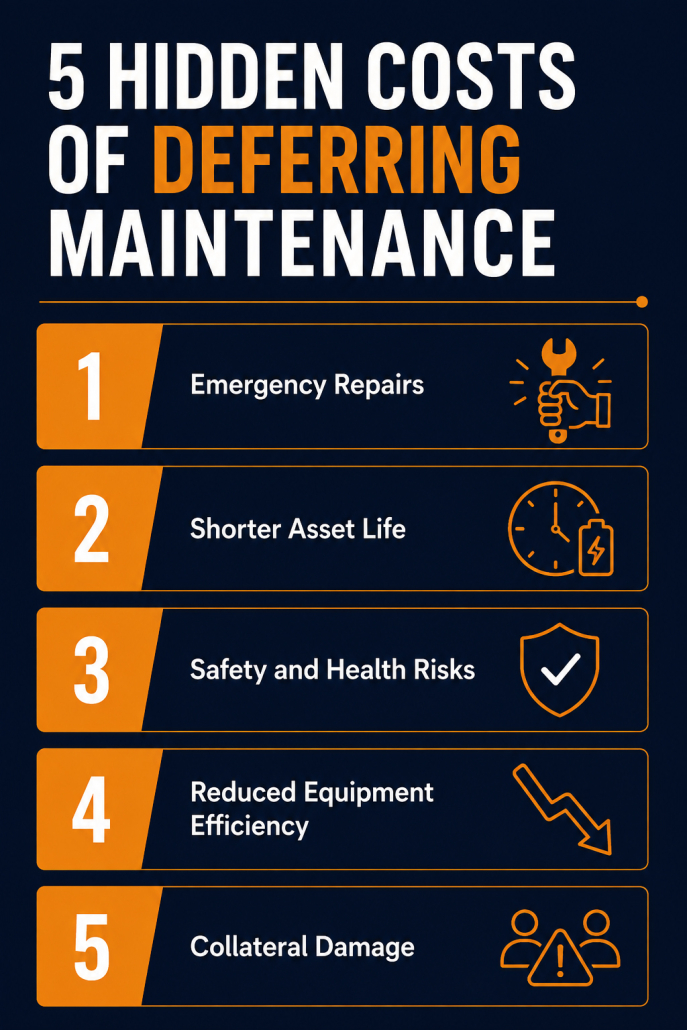
What Is HOA Deferred Maintenance?
Deferred maintenance refers to repairs that should be completed but have been delayed beyond their recommended timeframe. Every condominium association is responsible for maintaining common elements such as roofs, siding, parking areas, elevators, decks, balconies, walkways, drainage systems, and mechanical equipment.
Like every building, these components have a predictable lifespan. Roofs wear out. Pavement cracks. Windows eventually fail. Elevators require modernization. Boilers and HVAC systems become less efficient over time.
When an association continually postpones these projects, maintenance costs often increase because small problems become much larger and more expensive repairs.
Why Associations Delay Repairs
There are several reasons why HOA deferred maintenance may be postponed.
Sometimes the association simply doesn’t have enough money in its reserve account to complete major projects. Other times, board members may be reluctant to increase condominium fees because they fear pushback from owners. In some communities, repairs are delayed because owners vote against special assessments or major capital improvements.
Regardless of the reason, deferred maintenance rarely saves money in the long run. In many cases, delaying repairs allows additional damage to occur, increasing the final cost of the project.
The Impact on Property Values
Deferred maintenance doesn’t just affect the appearance of a condominium complex—it can also affect market value.
Buyers often notice aging roofs, deteriorating siding, cracked pavement, worn decks, or outdated common areas. Even if an individual unit has been beautifully renovated, concerns about the overall condition of the community may discourage buyers or lead them to submit lower offers.
Communities that consistently invest in maintenance often remain more attractive to buyers and may experience stronger long-term property values.
Special Assessments Can Be Expensive
One of the biggest financial risks associated with deferred maintenance is the possibility of a special assessment.
A special assessment is an additional charge levied against unit owners to pay for major repairs when reserve funds are insufficient. Depending on the size of the project, owners may be required to contribute thousands—or even tens of thousands—of dollars.
Projects such as roof replacements, building envelope repairs, elevator modernization, parking lot reconstruction, or structural work can easily exceed the association’s available reserves.
For buyers, understanding whether an assessment is being discussed or planned is an important part of the due diligence process.
Reserve Funds Matter
A well-managed condominium association typically maintains reserve funds to help pay for future capital improvements. Reserve accounts are designed to spread the cost of long-term repairs over many years rather than forcing owners to absorb a large unexpected expense.
One useful indicator is whether the association regularly contributes to its reserves and plans for predictable replacements based on the expected life of major building components.
While no reserve account can eliminate every unexpected expense, adequate reserves generally place a community in a stronger financial position.
Financing Can Become More Difficult
Deferred maintenance may also affect financing.
Some mortgage lenders carefully review the financial health of condominium associations before approving loans. Concerns about major deferred maintenance, inadequate reserves, ongoing litigation, or structural issues can complicate financing or reduce the number of loan programs available to prospective buyers.
A community with strong financial management may appeal to a broader range of buyers, while one with unresolved maintenance issues could experience a smaller pool of qualified purchasers.
Questions Buyers Should Ask
Before purchasing a condominium, buyers should consider asking questions such as:
- Are there any planned special assessments?
- How well funded are the reserve accounts?
- Have reserve studies been performed?
- What major projects have recently been completed?
- What large repairs are anticipated over the next several years?
- Are there ongoing water intrusion, structural, or roofing issues?
- Have monthly condominium fees increased significantly in recent years?
Reviewing the association’s budget, financial statements, meeting minutes, and reserve information can provide valuable insight into the overall health of the community.
Low Condo Fees Aren’t Always a Bargain
Many buyers naturally compare monthly condominium fees when evaluating different communities. While lower fees may appear attractive, they don’t always represent the best long-term value.
A condominium with slightly higher monthly fees may actually be better positioned financially because it consistently invests in maintenance and contributes appropriately to reserve funds.
Conversely, unusually low fees may indicate that necessary maintenance has been postponed or reserves have not been adequately funded.
The goal isn’t necessarily to find the lowest monthly fee—it’s to understand what those fees support.
Final Thoughts
Deferred maintenance is one of the most overlooked aspects of purchasing a condominium, yet it can have a lasting impact on both your finances and your property’s future value. Looking beyond the individual unit and evaluating the financial health of the association is an important part of making an informed buying decision.
Every condominium community is different. Some associations proactively plan for future repairs, maintain healthy reserve funds, and complete projects before problems become major expenses. Others may struggle to keep pace with aging infrastructure, resulting in deferred maintenance and costly special assessments.
If you’re considering purchasing a condominium, taking the time to review the association’s financial documents, reserve funding, and maintenance history can provide valuable insight and help you make a more confident investment decision.
Purchasing Opportunities: North Andover Condos for Sale • Andover Condos for Sale • Haverhill Condos for Sale
 Randy Tibbetts is an independent real estate broker providing professional residential & commercial real estate services in MA
 ADDRESS